
If you're hesitant to bring up captives with your clients or prospects, there's probably a reason why. Actually, there are probably three.
I've had this conversation with hundreds of independent agents. Good agents. Agents with 20-year relationships and strong books of business. And when I ask why they haven't introduced captives to their best clients, I hear the same three concerns.
- "I'm not sure I have a client or prospect big enough for a captive."
- "If a client asks me a captive question I can't answer, I look bad."
- "I'm not bringing my best client into a captive just so a broker can take them."
If one of those sounds familiar, you're in good company. Let's work through each one.
"Do I even have anyone big enough for a captive?"
You may have captive-ready clients in your book right now and not realize it.
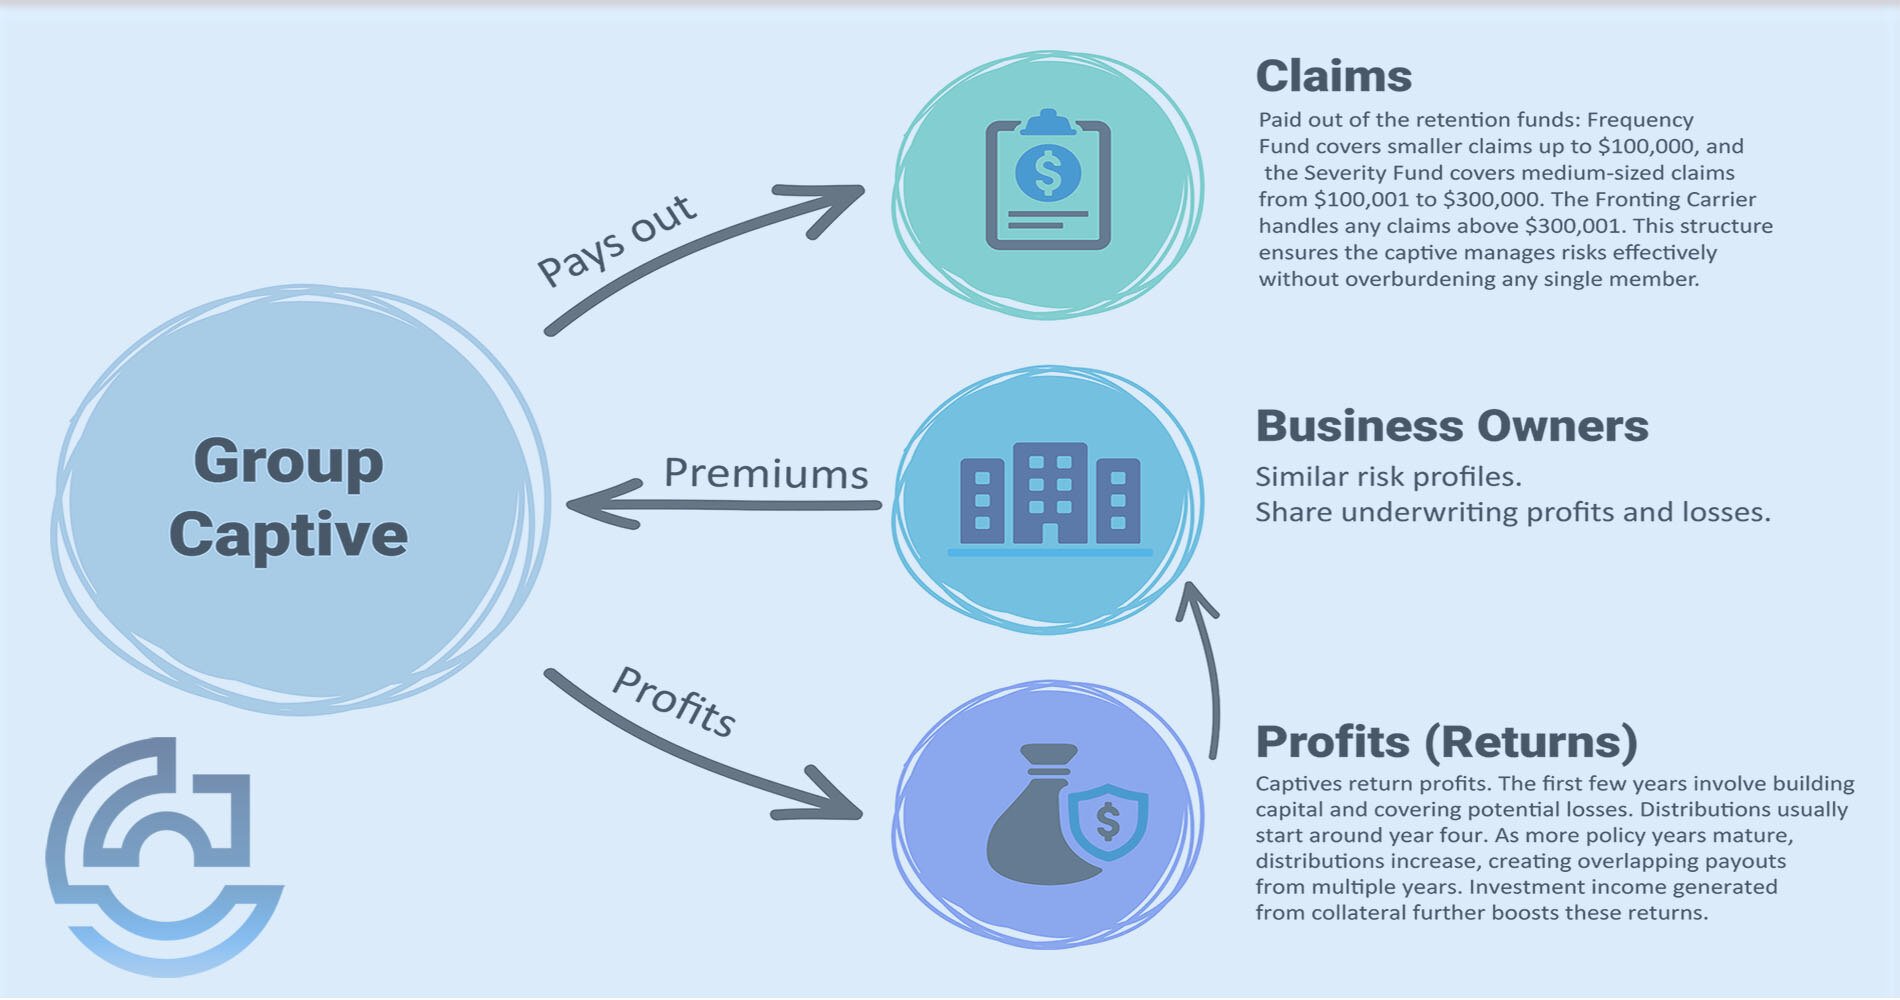
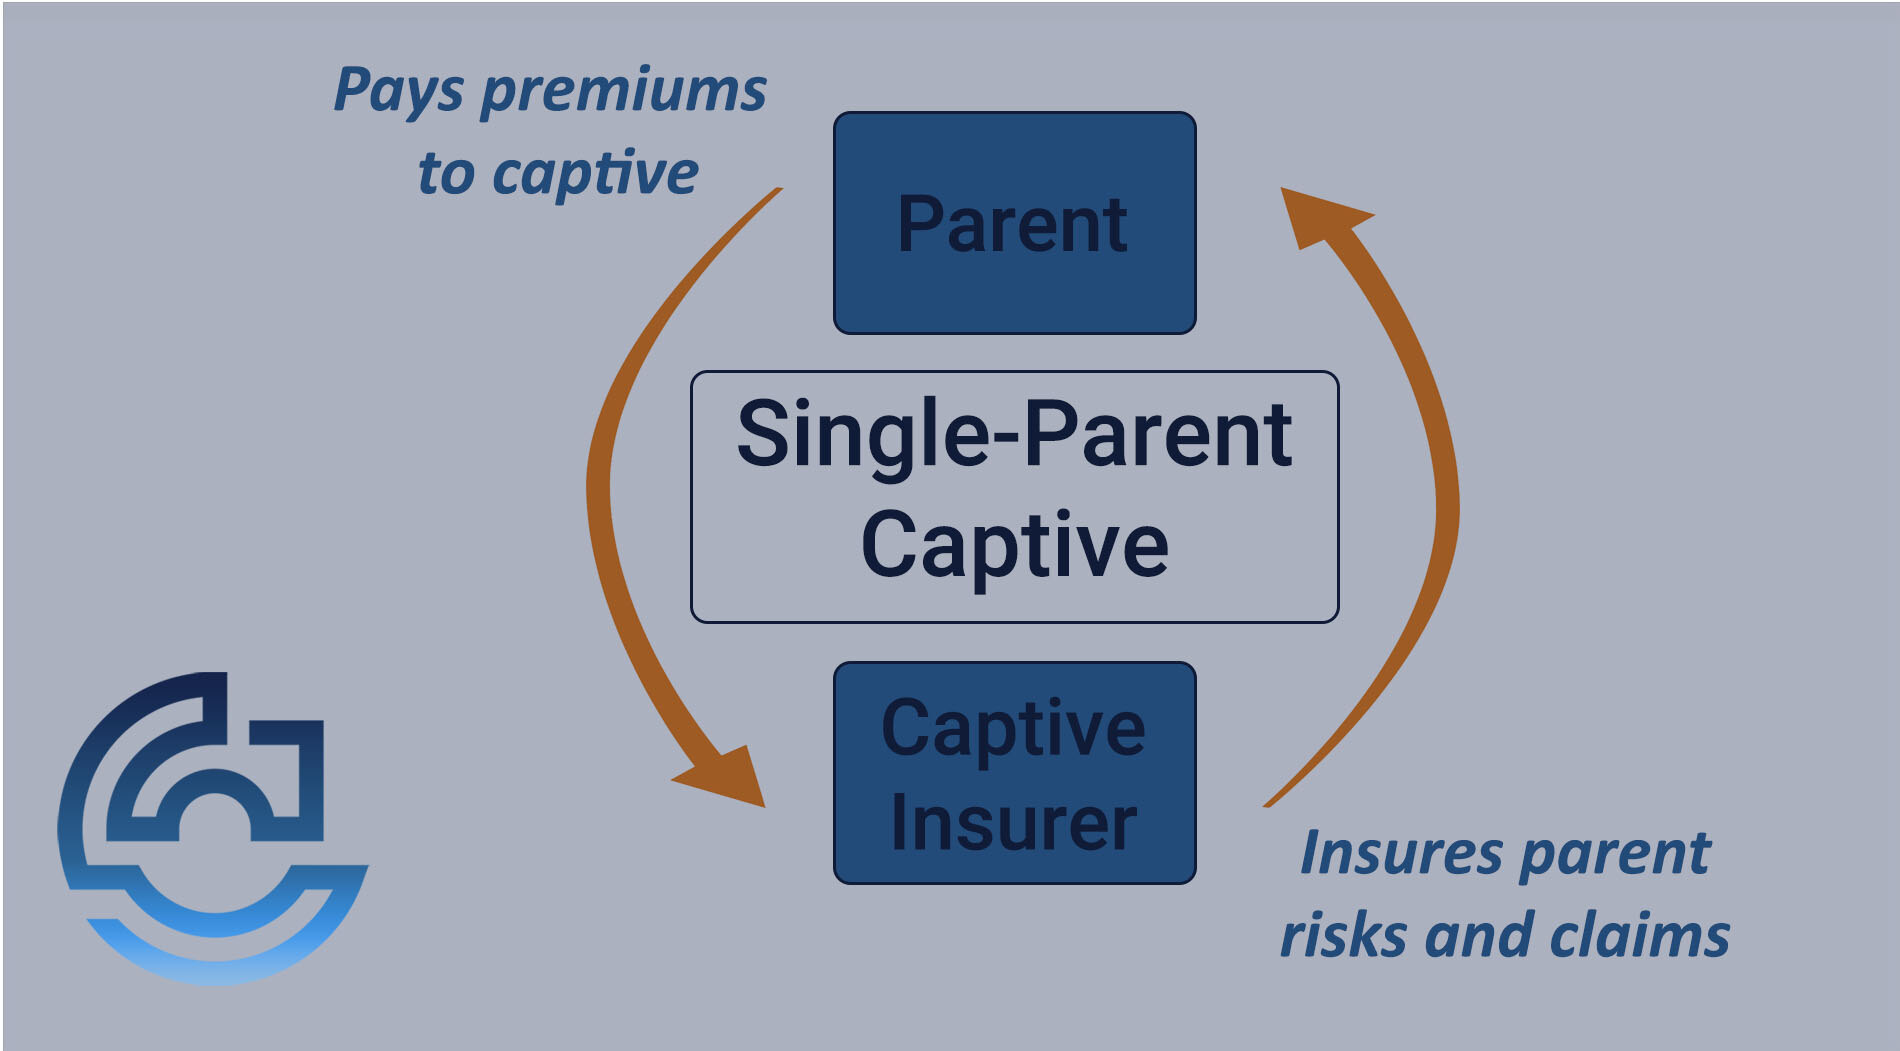
When many agents hear the word "captive," they picture a Fortune 500 company. That used to be true, but group captives have changed the conversation. Today, small and mid-sized businesses can join with other well-run companies, share risk, and participate in the financial results of their insurance program.
So what makes a client a good captive candidate? Here's how I'd work through your book.
- Start with frustration. Think about the clients who have said, "We rarely have claims, but our premiums keep going up." That's often your first clue.
- Look at how they operate. Well-run businesses that take safety and risk management seriously tend to be stronger captive candidates.
- Check their loss history. A favorable loss history over the past several years is another positive indicator.
- Then look at premium. Around $250,000 a year in workers' compensation, general liability, and auto combined is a good place to start.
If a client's name came to mind while you read that list, write it down. That's where your first captive conversation starts.
And if nobody in your book meets that threshold today, don't stop there. Use the same filter when you're prospecting. In fact, some of your best captive opportunities may be businesses you haven't won yet.
"What if my client asks something I can't answer?"
It's perfectly acceptable to say, "Good question. Let me get you the right answer."
Good advisors do that every day.
I understand why this concern sticks, though. You've spent years becoming the person your clients call when they have a question about insurance. Sitting across from your best client and not knowing the answer can feel uncomfortable.
But here's something you should know before you have that conversation: you don't need to become a captive expert before you bring up the strategy.
Your job is to recognize a potential fit, start the conversation, and stay at the center of the relationship. Your captive partner should provide the expertise and support behind you.
At Captive Coalition, we've built resources for exactly this situation—from the basic "What is a captive?" question to more detailed financial conversations with a CFO.
The goal isn't to turn you into an actuary or captive administrator. It's to help you understand enough to have a confident first conversation and know where to go when the questions get more complex.
And when a question comes up that you can't answer, you're not on your own. Our team is there to help you get the right answer quickly—so you can take it back to your client.
That's what a good captive partnership should look like.
"What if a broker takes my client?"
This concern is real, and I'd rather you hear that directly.
Some agents have learned about the risks of captive relationships the hard way. Others assume it's simply how captives work.
It doesn't have to be.
Some legacy captive arrangements were built around a model where the agent essentially handed over the client relationship. The agent provided the information, the captive manager handled the business, and the agent was left on the sidelines.
That's how captives developed a reputation for taking clients away from independent agents.
But that's not how every captive works.
At Captive Coalition, we built our program around a different principle: the independent agent stays at the center of the client relationship.
That's why our Five Rules matter so much.
- We only work with independent agents. No corporate brokers and no in-house producers.
- We don't accept surprise BORs. If you brought the relationship, it's yours. There are a few narrow exceptions, and we spell them out in our rules.
- Every client must have an independent agent. We don't take deals directly from businesses.
- We don't compete with you. We don't hold back leads or redirect clients.
- It's your client. Whether they join a group captive or eventually grow into their own captive, your name stays on the relationship.
If you're considering bringing a captive opportunity to your client, these are the questions you should be asking any captive partner—not just us.
How will you protect my relationship with my client?
Get the answer before you bring the opportunity forward.
What happens if you don't bring up captives at all?
That is the fourth question you need to ask yourself, and it's probably the most important one.
Doing nothing is an option. But it comes with a risk.
I see it too often, and I hear about it just as regularly. Other agents are prospecting clients who are sitting in your book right now. And your clients are looking for answers on their own.
Remember why your captive-ready clients may already be frustrated.
They run a tight operation. They invest in safety. They manage their people and their risks carefully. Yet their insurance premiums still continue to increase.
They want more control. They want more transparency. They want to understand where their insurance dollars are going and whether their strong performance should translate into better financial results.
That's a real problem for them.
And whoever helps them solve it earns the opportunity to strengthen the relationship.
I learned that the hard way. I lost a $300,000 client because I wasn't ready for a conversation I didn't even know was coming.
That experience changed the way I look at opportunities like this.
The good news is that getting ahead of the conversation is easier than you might think.
You're two minutes away from a productive captive conversation
We built a pricing calculator specifically for independent agents.
It's an agent-ready business development tool designed to help you identify whether a captive conversation is worth having with a particular client.
Here's what it gives you:
- Numbers you've never had. In about two minutes, you'll see what a captive could have meant for your client.
- Numbers that belong to your client. You'll see what they potentially could have retained over the past five years instead of paying it away through traditional insurance costs.
- An easy way to start the conversation. The results come back as a PDF designed to go directly to your client. You're not calling simply to talk about insurance. You're calling because you've found something worth discussing.
- Answers before they ask. Clients tend to come back with many of the same questions. The calculator includes a guide to help you prepare for the two questions we hear most often.
And I know what you might be thinking after reading that last section.
Is this really a tool I can use with my client?
Yes.
You run the numbers. The results are yours. The report goes to your client with your name on it.
We're here to support you—not take over the relationship.
No account is required.
Pull up the name you wrote down earlier and run the numbers.

It's always your client. Never ours.
Related Resources
- Identifying Your Best Clients for a Captive Insurer: If you're still wondering who in your book might fit, start here.
- Captive Insurance 101: Helping Clients with Confidence: For when you want to build your confidence before having that first conversation.
- The Five Rules of Captive Coalition: The full rules, including how we handle the rare exceptions.